
Post-closing trial balance explanation, example and purpose
It is used to ensure the balances are correct before entering into the new period. Each type of trial balance plays a vital role in displaying a company’s financial posture at specific intervals, providing insight into the different phases of the accounting regimen. The adjusted trial balance does not affect a company’s retained earnings. It has no effect on the retained earnings account because it separates the revenue and expense accounts. The post-closing trial balance, on the other hand, changes this account. As previously stated, it accomplishes this by shifting revenue and expenses to the retained earnings account.
Purpose in Financial Reporting
The post-closing trial balance confirms that your financial records are accurate and that all temporary accounts are fully closed. Since this report only includes permanent accounts, it ensures your books are balanced before moving into the next accounting period. This step reduces errors that could lead to compliance issues or financial misstatements. In conclusion, the trial balance is an essential tool used in accounting to ensure the accuracy of financial statements. It includes two columns, the debit column, and the credit column, which list all the accounts and their respective balances.
- Thus, it provides the summary of your general ledger accounts as it showcases the accounts and their balances.
- Furthermore, a trial balance also includes the account number of each of the general ledger accounts.
- It has no effect on the retained earnings account because it separates the revenue and expense accounts.
- For information, see Financial Report Builder and Financial Statement Layouts.
- It also serves as the foundation for preparing financial statements.
- However, the balancing of your trial balance does not imply that your accounting records are accurate.
Calculate total debits and credits
It is prepared after all closing entries have been posted to the ledger, which zeroes out temporary accounts and transfers their balances to permanent accounts. The post-closing trial balance is Certified Bookkeeper an essential tool in the accounting cycle, providing a final check on the accuracy and completeness of the financial records. By ensuring that all temporary accounts are closed and permanent accounts are balanced, the post-closing trial balance prepares the accounting system for the next period’s transactions. One common issue encountered during the post-closing trial balance is the presence of unbalanced accounts. This can occur if there were errors in the adjusting or closing entries, leading to discrepancies between debits and credits. To troubleshoot this, it’s crucial to re-examine each entry for accuracy and ensure that all temporary accounts have been properly closed.
What common accounts are included in the post-closing trial balance?
- Such inaccuracies can lead to discrepancies in financial reports, potentially resulting in flawed decision-making by stakeholders.
- This process ensures that all debits and credits are accurately recorded and balanced, verifying the integrity of the financial statements.
- Pre-closing trial balances are prepared before the closing entries are made, offering a comprehensive view of all accounts at the end of an accounting period.
- At year-end, these accounts move their totals to the shareholders’ equity.
- Some of the important accounts that your business management can track include purchases, debtors, sales, etc.
- So, your financial transactions are recorded accurately in the general ledger accounts if the debit column of your equates to its credit column.
At the end of a period, revenue, and expense ledger accounts are removed and closed. The post-closing trial balance is just a list of the remaining accounts. A post-closing trial balance is an inventory of all balance sheet accounts with non-zero balances at the end of a reporting period. It ensures that the sum of all debit and credit balances equals zero.
Why is a post closing trial balance performed?
A post-closing trial balance is a listing of all balance sheet accounts containing non-zero balances at the end of a reporting period. It is used to verify that the total of all debit balances equals the total of all credit balances, which should be net to zero. A post-closing trial balance is used to ensure that all temporary accounts have been closed and that the total debits equal the total credits.
Accounts like cash, accounts receivable, inventory, accounts payable, and owners equity are typical examples of accounts included retained earnings in the post-closing trial balance. This generally occurs at the end of the accounting period, after the financial statements have been prepared. A trial balance is a working report that lists all your ledger accounts and their current balances to check your bookkeeping’s accuracy. Thus, your business management can undertake comparative analysis and peer analysis with the help of the trial balance sheet. Such an analysis helps your management to understand the business trends and accordingly take the necessary actions. These decisions may be regarding your manufacturing costs, business expenses, incomes, etc.
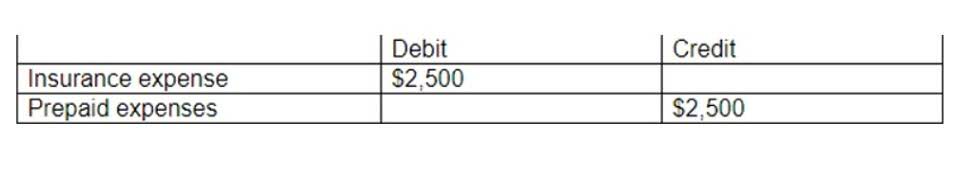
The differences between the adjusted and post-closing trial balances include the following. One way to detect errors is to compare the unadjusted trial balance to the adjusted trial balance. If the two balances do not match, there may be errors that need to be corrected. For instance, your purchases account would showcase an excess debit of $10,000 if you overstate your purchases in the books by $10,000.
How are revenue accounts closed in a trial balance?
They’re vital for correct financial statements, affecting income and retained earnings statements. Now that the post closing trial balance is prepared and checked for errors, Paul can start recording any necessary reversing entries before the start of the next accounting period. Since temporary accounts are already closed at this point, the post-closing trial balance will not include income, expense, and withdrawal accounts. It will only include balance sheet accounts, a.k.a. real or permanent accounts. Preparation of the post-closing trial balance ensures that all temporary accounts, such as revenue and expense accounts, have been closed out to the retained earnings account.
What is the Purpose of the Post-Closing Trial Balance?
Remember, your general ledger accounts are recorded in the following order in your trial balance sheet. As with all financial accounting, the debits must equal the credits. If it’s out of balance, something is wrong and the bookkeeper must go through each account to see what got posted or recorded incorrectly. The post-closing trial balance a post-closing trial balance reports: is prepared after the preparation of financial statements and posting of closing entries, marking the end of the accounting cycle.